

If you were hurt in a car accident while working, you may have two claims, not one. Workers’ compensation can pay your medical care and part of your lost wages regardless of fault. If another driver caused the crash, you may also bring an injury claim against them for losses comp doesn’t cover, like pain and suffering. Report the injury to your employer within 30 days, and get advice before settling either claim, because the two affect each other.
Introduction
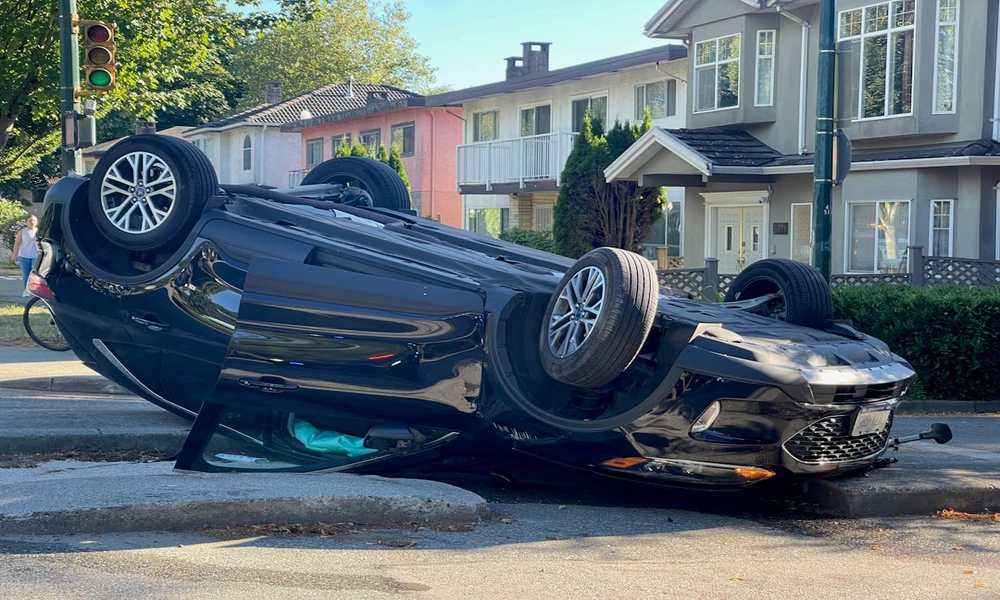
You were driving to a client’s office, making a delivery, or heading to a second job site when another driver ran a red light. Now you’re hurt, out of work, and getting calls from two different insurance companies: one about workers’ comp and one representing the driver who hit you.
A car accident while working puts you at the intersection of two legal systems that most people never have to think about. Workers’ compensation covers job injuries without anyone proving fault. A personal injury claim holds a careless driver responsible for the full harm they caused. In many work-related crashes, you can use both.
That’s good news, but it comes with traps. The claims have different deadlines, different rules and an overlap that can quietly cost you money if it’s handled wrong. Here’s how everything connects.
Does Workers’ Comp Cover a Car Accident While Working?
Generally, yes. If you were driving as part of your job, such as making deliveries, traveling between job sites, visiting clients or running an errand for your employer, a crash is usually treated as a work injury. Workers’ comp covers it whether you, the other driver or nobody was at fault.
That no-fault feature is what makes workers’ comp so valuable. You don’t have to prove anyone was careless. You only have to show that the injury arose out of and occurred in the course of your employment.
Workers’ comp benefits generally include medical treatment for the injury, temporary disability payments while you can’t work (usually about two-thirds of your average weekly wages, up to a state maximum), permanent disability benefits if you don’t fully recover, and in some cases a voucher for retraining.
What comp does not pay is just as important. It doesn’t pay for pain and suffering, and it doesn’t replace all of your lost income. That gap is where a second claim can matter.
The Commute Problem: California’s Going and Coming Rule
Your regular commute to and from work usually doesn’t qualify for workers’ comp. California calls this the going-and-come rule. But there are well-established exceptions, and crashes during a work-related errand, in a vehicle your job requires, or while traveling for work are often covered.
Common exceptions include:
- Special errand. Your employer asked you to do something during the commute, like pick up supplies or stop at a client’s location.
- Required vehicle. Your job requires you to bring your own vehicle to work, for example, to drive to sites during the day.
- Traveling employee. You were on a business trip or traveling between work locations.
- Employer-provided transportation. You were riding in a vehicle your employer arranged.
These cases turn on details, and the Workers’ Compensation Appeals Board regularly decides disputes over whether an exception applies. If your claim is denied because you were commuting, don’t assume that’s the final word. Even if comp doesn’t apply, you can still pursue an injury claim against the driver who caused the crash.
Suing the Other Driver: Your Third-Party Injury Claim
Workers’ comp usually prevents you from suing your employer. It does not stop you from suing an outside party who caused the crash, such as another driver. This is called a third-party claim, and it can recover losses that workers’ comp doesn’t cover, including pain and suffering and the full amount of your lost income.
California law expressly preserves this right. Under Labor Code section 3852, receiving workers’ comp doesn’t take away your claim against a third party whose negligence caused your injury.
Possible third parties in a work-related crash include the at-fault driver, that driver’s employer if they were working, a vehicle or parts manufacturer if a defect played a role, and a public agency if a dangerous road condition contributed.
The usual exception is a coworker. If a fellow employee caused the crash while you were both working, workers’ comp is generally your only remedy against them and your employer. The same goes for crashes caused solely by your own mistake: comp still covers you, but there’s no third party to sue.
Third-party claims follow normal injury rules. California’s pure comparative fault rule applies, and most lawsuits must be filed within two years of the crash.
Workers’ comp covers your job injury. A third-party claim covers what the other driver took from you.
How the Two Claims Affect Each Other: Liens and Credits
You can’t collect twice for the same loss. If you recover money from the at-fault driver, the workers’ comp insurer can generally be repaid for benefits it already paid, and it may take a credit against future benefits. How those claims are coordinated can affect what you actually keep.
The Labor Code gives the comp insurer several ways to get reimbursed: suing the third party itself, joining your lawsuit, or asserting a lien on your recovery. After a third-party settlement, the insurer can also petition for a credit so it doesn’t pay future benefits until that credit is used up, a process the California Lawyers Association has described in detail.
Those rights aren’t automatic or unlimited. If your employer’s own negligence contributed to the crash, its insurer’s reimbursement rights can be reduced. And the comp lien is often negotiable, especially when the insurer benefits from the work your lawyer did to win the third-party case.
The practical lesson: don’t settle one claim without considering the other. Settling the injury claim for a number that looks good can shrink once the comp lien is paid and future benefits stop. Settling the comp case first can affect how medical costs are handled in the injury case.
What to Do After a Car Accident on the Job
Get medical care, report the injury to your employer in writing within 30 days, and file a DWC 1 claim form. Then document the crash just as you would any car accident, because you may need that evidence for a third-party claim against the other driver.
- Get treatment and say it happened at work. Tell every provider the crash happened while you were working.
- Report it to your employer. California generally requires you to report a work injury within 30 days. Do it in writing and keep a copy.
- File the claim form. Your employer must give you a DWC 1 claim form within one working day of learning about the injury. Filing it opens your comp case, and the Division of Workers’ Compensation explains that your employer must authorize up to $10,000 in treatment while the claim is considered. If the claim isn’t denied within 90 days, it’s generally presumed covered.
- Document the crash. Photos, the other driver’s insurance, witness names and the police report number.
- File the SR-1 if required. The DMV’s SR-1 is due within 10 days if anyone was hurt or damaged tops $1,000.
- Be careful with both insurers. Don’t give a recorded statement to the other driver’s insurer, and don’t sign settlement papers in either case without advice.
One more deadline: if you don’t file the claim form, you generally have one year from the injury to do so, according to the DIR’s fact sheet. Waiting that long is rarely a wise idea.
Why One Firm Handling Both Claims Helps
When the same firm handles both your workers’ comp case and your injury claim, it can coordinate the two from day one. That means consistent medical evidence, settlements timed to protect your net recovery, and a lien negotiated by someone who knows exactly what the comp insurer has paid and what it still owes.
When two separate lawyers handle the cases, or you handle one yourself, details slip. A statement in the comp case can be used in the injury case. A third-party settlement can trigger a credit that nobody planned for. Medical treatment approved in one system may be disputed in the other.
Oracle Law Firm handles both workers’ compensation and car accident cases, which is exactly the overlap these crashes create. No lawyer can promise an outcome, but coordinated claims protect more of what you’re owed.
Getting Both Claims Right
Two takeaways. First, a crash while working often gives you two paths: workers’ comp for guaranteed basic benefits and a third-party claim for the full harm the other driver caused. Second, those paths cross. Liens, credits and timing decide how much you actually keep.
Oracle Law Firm represents injured workers and drivers across Orange County, Los Angeles and the Inland Empire.
Been in an accident or hurt on the job? You don’t have to navigate insurance companies alone. Oracle Law Firm fights to get you the compensation, control, and clarity you deserve.
Get a Free Consultation or call 888.597.4099.
Disclaimer: This article is for general information only and is not legal advice. Reading it does not create an attorney-client relationship. Every case depends on its own facts, and past results do not guarantee future outcomes.
Frequently Asked Questions
Can I get workers’ comp and sue the other driver at the same time?
Often, yes. Workers’ comp covers your work injury regardless of fault, and California law preserves your right to sue a third party, such as another driver, whose negligence caused the crash. The comp insurer may be reimbursed from your third-party recovery, so the two claims should be coordinated.
Am I covered by workers’ comp if I crashed on my way to work?
Usually not for an ordinary commute, under California’s going-and-come rule. But exceptions often apply, such as when you were running an errand for your employer, your job required you to bring your vehicle, or you were traveling for work.
Can I sue my employer for a car accident while working?
Generally no. Workers’ comp is usually the exclusive remedy against your employer and coworkers. You can, however, pursue a claim against an outside party, such as the other driver or a vehicle manufacturer, if they caused the crash.
Does workers’ comp pay for pain and suffering?
No. Workers’ comp pays medical treatment, a portion of lost wages and disability benefits, but not pain and suffering. A third-party injury claim against the at-fault driver is how injured workers typically pursue those damages.
How long do I have to report a work-related car accident?
Report the injury to your employer within 30 days. You generally have one year to file the DWC 1 claim form, and most lawsuits against an at-fault driver must be filed within two years. Acting quickly protects both claims.